Cashier Shift Close: Cash and Noncash Reconciliation
Reconcile cashier shifts using expected cash, counted cash, noncash settlement and documented exceptions, keeping payment corrections separate from sales changes.
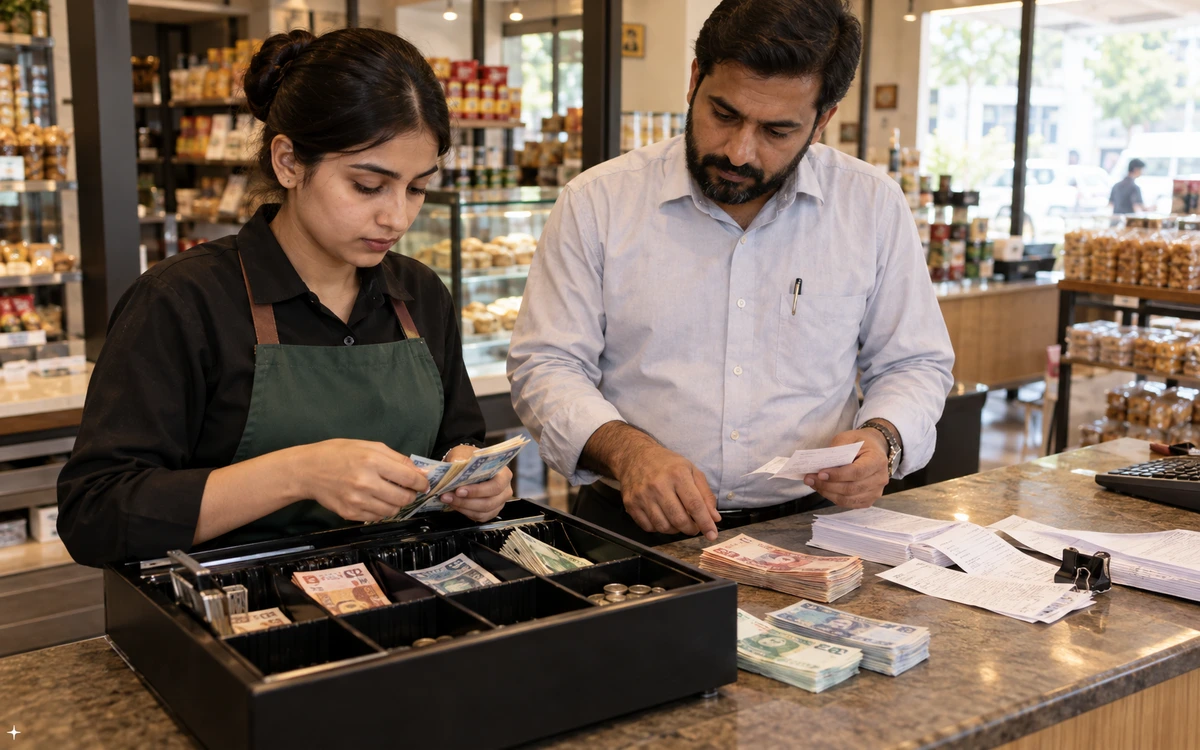
Close the shift with evidence.
Choose a stage to explore the practical checks.
Define the cashier's responsibility
Agree which drawer, counter, user and trading window belong to the shift. State how opening cash and authorised cash movements are recorded. If several people share a counter, describe the handover and accountability rules before testing. A sales total alone may cover activity outside the cashier's assigned responsibility. The close process should compare records from the same operating boundary and make any shared responsibility visible rather than hiding it inside a branch-wide total.
Read this part of the guideDistinguish sale value from expected cash
Prepare a small shift containing cash and the noncash payment methods relevant to the business. Include a permitted refund and an authorised cash movement. Ask the operator to explain how expected cash is derived under the proposed workflow. The final sales value and the amount expected in a drawer need not be identical. Staff should be able to explain the difference using recorded events instead of adjusting the counted figure to match a convenient report.
Read this part of the guideReview noncash records independently
Compare the noncash amounts recorded by the POS with the evidence used by the business's payment process. Confirm whether any payment integration is included or whether reconciliation is manual. Do not assume that choosing a payment-method button means a bank or external service accepted the payment. Keep external references where the agreed process needs them. Assign an owner to missing or disputed settlement evidence so the issue can be investigated without altering the underlying sale unnecessarily.
Read this part of the guideClosing a cashier shift requires more than counting cash. The reviewer also needs to understand recorded payment methods, refunds and authorised movements. A proposed POS workflow should make those records clear enough for another person to review. Test the complete close process with iPOS using the settlement categories your business actually uses.
Define the cashier's responsibility
Agree which drawer, counter, user and trading window belong to the shift. State how opening cash and authorised cash movements are recorded. If several people share a counter, describe the handover and accountability rules before testing. A sales total alone may cover activity outside the cashier's assigned responsibility. The close process should compare records from the same operating boundary and make any shared responsibility visible rather than hiding it inside a branch-wide total.
Distinguish sale value from expected cash
Prepare a small shift containing cash and the noncash payment methods relevant to the business. Include a permitted refund and an authorised cash movement. Ask the operator to explain how expected cash is derived under the proposed workflow. The final sales value and the amount expected in a drawer need not be identical. Staff should be able to explain the difference using recorded events instead of adjusting the counted figure to match a convenient report.
Review noncash records independently
Compare the noncash amounts recorded by the POS with the evidence used by the business's payment process. Confirm whether any payment integration is included or whether reconciliation is manual. Do not assume that choosing a payment-method button means a bank or external service accepted the payment. Keep external references where the agreed process needs them. Assign an owner to missing or disputed settlement evidence so the issue can be investigated without altering the underlying sale unnecessarily.
Test a misclassified payment
Record a representative transaction under an incorrect payment method, then demonstrate the approved correction. Inspect who can authorise it and what a later reviewer sees. A payment-classification error should remain distinguishable from a cancelled sale or a stock return. Ask the provider to explain the supported method and its effect on close reports. This scenario often exposes a practical training need that does not appear during a demonstration containing only correctly entered transactions.
Investigate before approving a difference
Compare counted cash with the expected amount and review the relevant evidence for any difference. Keep the original count, explanation and approval separate. Decide which differences require a recount or another reviewer. The business should approve those rules according to its operating needs. A software adjustment that makes a report balance is not, by itself, an explanation of what happened. Retain unresolved items with a responsible person and a next action.
Use the close record for better operations
Keep the accepted shift pack accessible for the next reviewer and for support investigations. Review recurring issues to improve payment-method training, drawer handovers or exception procedures. Avoid assigning a cause without evidence. For a branch network, agree a consistent close format while documenting genuine local differences. Ask iPOS to demonstrate the reports and access controls required for this review in the proposed configuration, including the connection between a summary and its underlying transactions.
Useful next steps
Prepare a sample shift with one payment error and one refund so iPOS can show how the proposed setup supports an explainable close. Discuss your requirements with iPOS.
More from Insights
Owner Mobile Apps for Connected POS and ERP Management
Connect owner decisions with iPOS Web POS, Infinity ERP and mobile access. Evaluate branch context, exceptions, permissions and useful management workflow…
Customer Mobile Apps for Stronger Retail Relationships
Plan a useful iPOS customer mobile app around real customer journeys, clear records and consistent service, with owner and customer responsibilities kept…
Ecommerce Stores, iPOS Web POS and Infinity ERP
Plan an ecommerce store alongside iPOS Web POS and Infinity ERP, with clear ownership of products, stock, orders, fulfilment and customer-facing informati…