Returns and Exchanges After a Retail Period Has Closed
Plan returns and exchanges across cashier shifts and reporting periods, preserving the original sale, approval evidence, stock movement and settlement relationship.
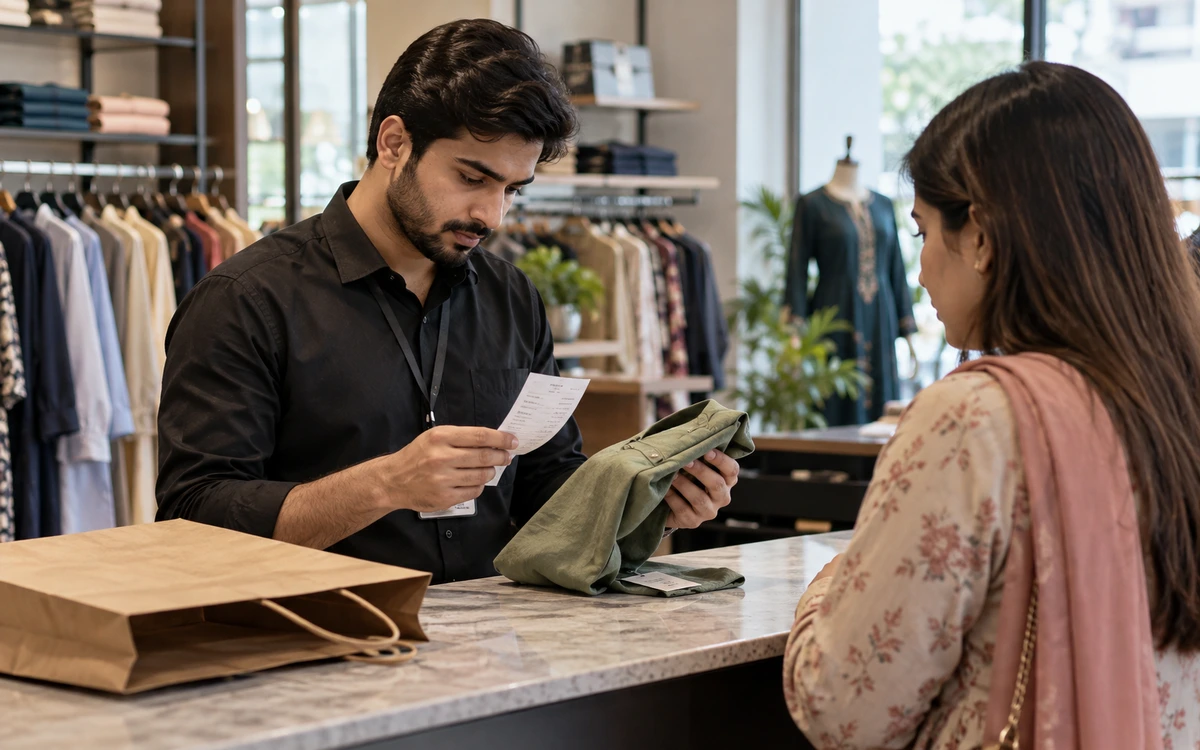
Bring the return back to its source.
Choose a stage to explore the practical checks.
Keep the original transaction identifiable
Choose a sale from an earlier period and locate it through the information staff will normally receive from a customer. Confirm what happens when a receipt is missing or the item description is ambiguous. A return should retain a meaningful relationship with the original document where the approved process requires it. Ask the provider to demonstrate the exact lookup and document history available in the proposed product, rather than assuming that every sale can be reconstructed from a stock record.
Read this part of the guideSeparate policy from software capability
Write down which returns the business allows, what evidence is needed and who may approve an exception. Have the appropriate adviser confirm any obligations relevant to the operation. The software demonstration should show how the agreed process is applied; it should not be used to invent the business's return policy. If a required control remains manual, record it explicitly so managers can decide whether the proposed workflow is practical at each branch.
Read this part of the guideTest the settlement and stock effects together
Process an ordinary return and inspect both the customer settlement and the stock movement. Include a product that is not immediately saleable again, such as a damaged item. Decide where that quantity should be recorded under the approved process. A refund does not necessarily mean the item belongs back on a selling shelf. Compare the resulting documents and reports so the team understands how the proposed setup distinguishes the financial adjustment from the physical treatment.
Read this part of the guideA customer can return an item after the original shift or reporting period has closed. The business still needs to explain the original sale and the later adjustment. Use this scenario when evaluating a proposed iPOS workflow, with the responsible finance person approving the treatment rather than leaving the counter team to improvise.
Keep the original transaction identifiable
Choose a sale from an earlier period and locate it through the information staff will normally receive from a customer. Confirm what happens when a receipt is missing or the item description is ambiguous. A return should retain a meaningful relationship with the original document where the approved process requires it. Ask the provider to demonstrate the exact lookup and document history available in the proposed product, rather than assuming that every sale can be reconstructed from a stock record.
Separate policy from software capability
Write down which returns the business allows, what evidence is needed and who may approve an exception. Have the appropriate adviser confirm any obligations relevant to the operation. The software demonstration should show how the agreed process is applied; it should not be used to invent the business's return policy. If a required control remains manual, record it explicitly so managers can decide whether the proposed workflow is practical at each branch.
Test the settlement and stock effects together
Process an ordinary return and inspect both the customer settlement and the stock movement. Include a product that is not immediately saleable again, such as a damaged item. Decide where that quantity should be recorded under the approved process. A refund does not necessarily mean the item belongs back on a selling shelf. Compare the resulting documents and reports so the team understands how the proposed setup distinguishes the financial adjustment from the physical treatment.
Include an exchange with a price difference
Return one item and sell another with a different price. Observe how the amount due to or from the customer is calculated and settled. Review any discount or promotion attached to the original purchase. Ask whether the exchange is represented as linked documents or another supported workflow, and record the method. The result should be understandable to the next cashier or manager without relying on an informal note that two unrelated transactions cancel each other.
Review the reporting-period boundary
Ask finance to inspect how the later return appears relative to the earlier sale. Identify any permissions governing changes to closed work and the records that remain visible. This guide does not prescribe the accounting treatment; that decision belongs to the responsible professional. The acceptance test should establish that the approved treatment can be followed in the proposed configuration and that a reviewer can distinguish the original activity from the subsequent correction.
Make exceptions easy to investigate
Keep a return reference, original document reference, reason, approval and settlement evidence where relevant. Decide who reviews unusual patterns and how a disputed case reaches support. Use a realistic test pack containing a normal return, an exchange and a period-boundary case for every shortlisted provider. This makes comparisons more consistent than accepting a demonstration of only the simplest refund button. Retain the accepted process for staff training and future configuration checks.
Useful next steps
Ask iPOS to demonstrate one real return scenario from an earlier reporting period with your finance and counter teams reviewing the result together. Discuss your requirements with iPOS.
More from Insights
Owner Mobile Apps for Connected POS and ERP Management
Connect owner decisions with iPOS Web POS, Infinity ERP and mobile access. Evaluate branch context, exceptions, permissions and useful management workflow…
Customer Mobile Apps for Stronger Retail Relationships
Plan a useful iPOS customer mobile app around real customer journeys, clear records and consistent service, with owner and customer responsibilities kept…
Ecommerce Stores, iPOS Web POS and Infinity ERP
Plan an ecommerce store alongside iPOS Web POS and Infinity ERP, with clear ownership of products, stock, orders, fulfilment and customer-facing informati…