Restaurant Recipe Costing Versus Menu Sales Reports
Separate restaurant menu sales from recipe consumption and cost assumptions, then test yields, substitutions and waste before choosing inventory and reporting modules.
The plate behind the margin.
Choose a stage to explore the practical checks.
Start with a representative menu item
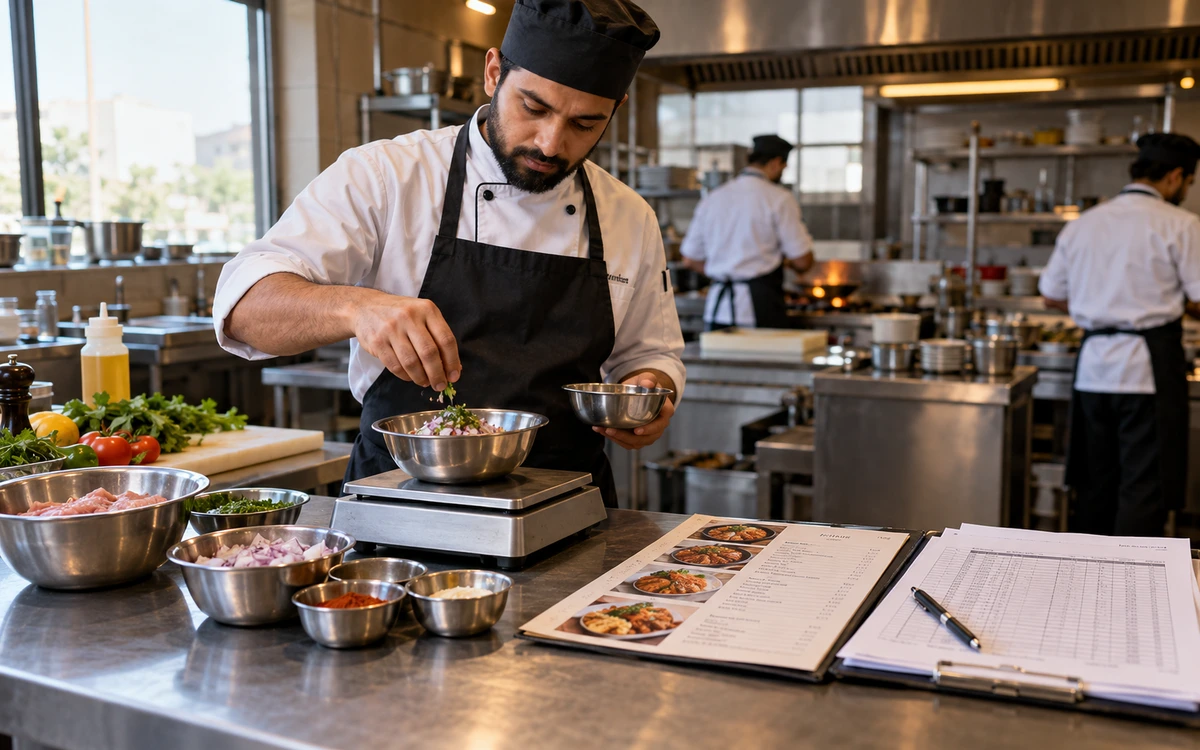
Choose an item that staff prepare regularly and record its intended ingredients, quantities and serving unit. Include a component prepared in batches if that is part of the recipe. Agree who owns the recipe record and approves changes. Avoid beginning with a large menu import before a small example has been tested. The implementation team needs to understand the relationship between the item sold and the stock records used by the kitchen.
Read this part of the guideMake units and yields explicit
Document the purchasing units, preparation units and expected yield relevant to the example. A product bought by weight and used in individual portions needs an agreed conversion. Preparation losses or batch yields should come from the restaurant's approved process, not an assumption inserted by the software provider. Test how the proposed configuration represents these relationships. If some calculations remain outside the product, keep that boundary visible so the resulting reports are interpreted appropriately.
Read this part of the guideSeparate expected use from actual movement
Sell the sample menu item and inspect the supported stock or recipe effect. Then compare it with a physical or operational record of actual use over an agreed period. Expected consumption based on a recipe is not automatically the same as measured kitchen consumption. The distinction matters when the team investigates waste, portion variation or an incorrect recipe. Ask the provider to explain exactly which records a proposed consumption report includes.
Read this part of the guideA menu item sold and the ingredients used to prepare it describe different records. A sales report can show demand without proving actual ingredient consumption or final profitability. If recipe costing matters to the restaurant, define it as a separate requirement and confirm the exact modules and operating process included in the proposed iPOS setup.
Start with a representative menu item
Choose an item that staff prepare regularly and record its intended ingredients, quantities and serving unit. Include a component prepared in batches if that is part of the recipe. Agree who owns the recipe record and approves changes. Avoid beginning with a large menu import before a small example has been tested. The implementation team needs to understand the relationship between the item sold and the stock records used by the kitchen.
Make units and yields explicit
Document the purchasing units, preparation units and expected yield relevant to the example. A product bought by weight and used in individual portions needs an agreed conversion. Preparation losses or batch yields should come from the restaurant's approved process, not an assumption inserted by the software provider. Test how the proposed configuration represents these relationships. If some calculations remain outside the product, keep that boundary visible so the resulting reports are interpreted appropriately.
Separate expected use from actual movement
Sell the sample menu item and inspect the supported stock or recipe effect. Then compare it with a physical or operational record of actual use over an agreed period. Expected consumption based on a recipe is not automatically the same as measured kitchen consumption. The distinction matters when the team investigates waste, portion variation or an incorrect recipe. Ask the provider to explain exactly which records a proposed consumption report includes.
Test substitutions and wastage
Use a scenario in which the kitchen substitutes an ingredient or records an item that cannot be sold. Confirm the approved operational treatment and ask how the proposed setup represents it. A substitution should not silently change the recipe for every future order unless that is the authorised intention. Decide who records an exception and who reviews it. The kitchen, purchasing and finance teams need a shared understanding of what was expected and what actually happened.
Interpret margin with its assumptions visible
Ask which cost basis, recipe version and transaction period are used in a proposed margin report. Include discounts and returns where relevant. Have the responsible finance person approve the interpretation. A menu item with a strong sales value may still require investigation if its consumption or cost assumptions are unreliable. Do not treat a single percentage as a complete profitability assessment without understanding the data and operating costs that sit outside that calculation.
Review recipes as an ongoing control
Assign responsibility for changes in ingredients, pack sizes, purchase costs and portions. Retain a small regression example that can be rerun after a configuration change. Use the findings to improve the recipe and the recording process together. Compare providers using the same sample menu item and exception scenarios. This produces a clearer decision than accepting a broad claim of restaurant inventory control without confirming whether the required recipe and consumption functions are included.
Useful next steps
Bring one recipe with its purchasing units and preparation yield to iPOS, and ask the team to demonstrate the specific costing and stock requirements you need. Discuss your requirements with iPOS.
More from Insights
Owner Mobile Apps for Connected POS and ERP Management
Connect owner decisions with iPOS Web POS, Infinity ERP and mobile access. Evaluate branch context, exceptions, permissions and useful management workflow…
Customer Mobile Apps for Stronger Retail Relationships
Plan a useful iPOS customer mobile app around real customer journeys, clear records and consistent service, with owner and customer responsibilities kept…
Ecommerce Stores, iPOS Web POS and Infinity ERP
Plan an ecommerce store alongside iPOS Web POS and Infinity ERP, with clear ownership of products, stock, orders, fulfilment and customer-facing informati…