Cycle Counts: From a Stock Difference to an Approved Fix
Build a cycle-count process with a clear boundary, independent review, movement checks and approved corrections rather than adjustments that hide stock differences.
Count. Review. Approve.
Choose a stage to explore the practical checks.
Define exactly what is being counted
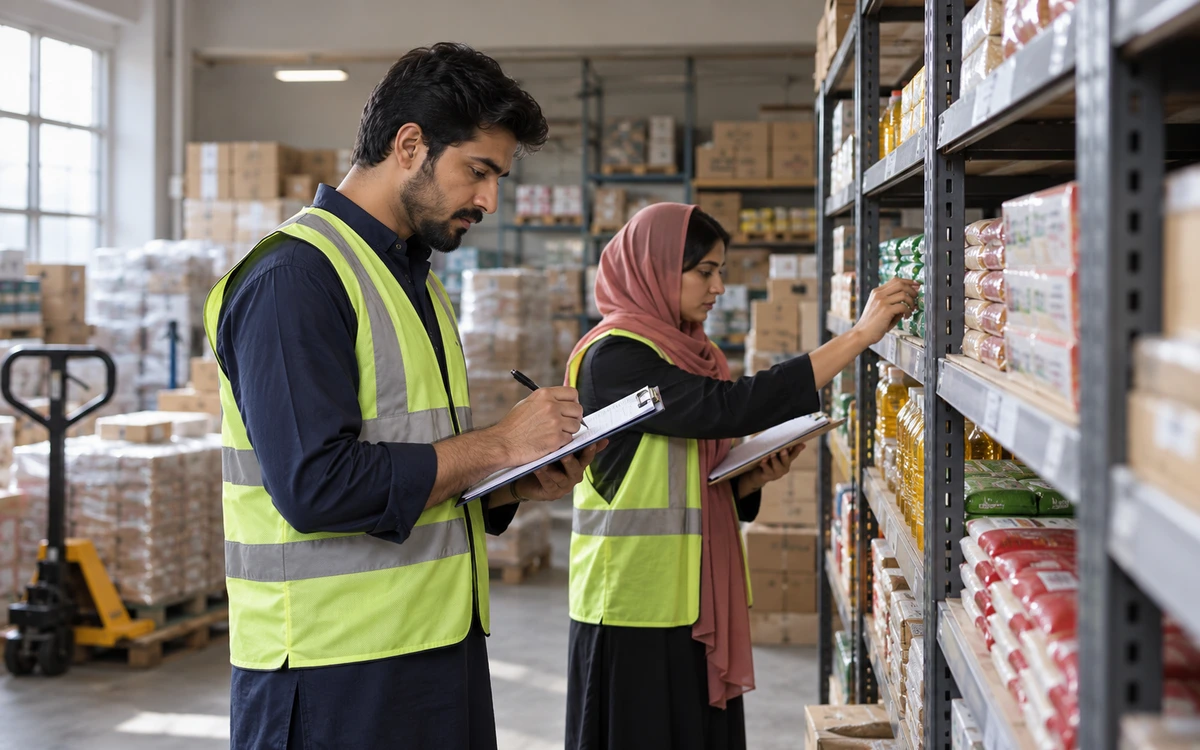
Choose the location, products and time boundary for the count. Decide how stock movement during the count will be handled and who authorises that method. Include stock in receiving areas, returns areas or other temporary locations where relevant. A count of shelf stock alone may not be comparable with a system quantity covering the whole branch. State the scope clearly so the team understands what the resulting difference actually describes.
Read this part of the guidePrepare a repeatable counting method
Decide how counters identify the item, unit and location. Test an ambiguous barcode and a product stored in more than one place. If a scanner or mobile audit device is proposed, confirm its compatibility and the supported workflow. Avoid assuming that access to a product list establishes a complete stock-audit process. Staff should be able to repeat the count consistently, and the business should retain enough evidence to review an unexpected result.
Read this part of the guideReview the timing of movements
Before accepting a difference, inspect the receipts, sales, returns and transfers that could fall near the count boundary. Check whether a transaction was entered late or assigned to a different location. Keep the original count and the movement review distinguishable. The purpose is to investigate the difference, not to search for any convenient transaction that makes it disappear. Unresolved timing questions should remain visible until the responsible person approves their treatment.
Read this part of the guideA stock count is useful when a difference leads to an explanation and an approved action. Simply replacing the system quantity with the counted quantity can hide the cause. Plan the count process before selecting reports or devices, then ask the iPOS team to demonstrate the controls needed for your warehouse, store or branch.
Define exactly what is being counted
Choose the location, products and time boundary for the count. Decide how stock movement during the count will be handled and who authorises that method. Include stock in receiving areas, returns areas or other temporary locations where relevant. A count of shelf stock alone may not be comparable with a system quantity covering the whole branch. State the scope clearly so the team understands what the resulting difference actually describes.
| Stage | Required evidence | Responsibility to define |
|---|---|---|
| Count | Original quantity, unit, location and count boundary | Who records the observation |
| Investigation | Recount and relevant movement review | Who explains or escalates the difference |
| Approval | Accepted reason and supporting record | Who authorises the proposed correction |
| Posting | Traceable adjustment under the approved process | Who completes and checks the final entry |
Prepare a repeatable counting method
Decide how counters identify the item, unit and location. Test an ambiguous barcode and a product stored in more than one place. If a scanner or mobile audit device is proposed, confirm its compatibility and the supported workflow. Avoid assuming that access to a product list establishes a complete stock-audit process. Staff should be able to repeat the count consistently, and the business should retain enough evidence to review an unexpected result.
Review the timing of movements
Before accepting a difference, inspect the receipts, sales, returns and transfers that could fall near the count boundary. Check whether a transaction was entered late or assigned to a different location. Keep the original count and the movement review distinguishable. The purpose is to investigate the difference, not to search for any convenient transaction that makes it disappear. Unresolved timing questions should remain visible until the responsible person approves their treatment.
Use a second look for significant exceptions
Agree which differences require a recount or another reviewer. The threshold and process should match the business's risks and operating capacity, rather than a number chosen by the software installer. Ask the provider to demonstrate the permissions and records relevant to the approved process. A reviewer should be able to understand what was counted, what changed and why a correction is proposed without relying entirely on the first counter's memory.
Approve the correction separately from the count
Identify who may authorise and post the final adjustment. Retain the reason and supporting evidence. Have finance review how stock-value effects are treated in the proposed configuration where those effects are within scope. Avoid giving every counter unrestricted adjustment access merely because they need to record a count. Keeping the count, investigation and approval distinguishable makes the process more accountable while still allowing ordinary stock work to continue.
Learn from the pattern of differences
Review recurring issues by product, location or process where the available evidence supports that comparison. Repeated errors may point to confusing units, a receiving practice or an incomplete transfer handoff. Do not label a cause without investigation. Use the findings to improve training and the next count cycle. Connect the exercise with transfer controls and unit-conversion checks so the business fixes the operating process as well as the final quantity.
Useful next steps
Bring a recent count sheet and an unexplained difference to iPOS so the proposed setup can be evaluated against the investigation your team needs to perform. Discuss your requirements with iPOS.
More from Insights
Owner Mobile Apps for Connected POS and ERP Management
Connect owner decisions with iPOS Web POS, Infinity ERP and mobile access. Evaluate branch context, exceptions, permissions and useful management workflow…
Customer Mobile Apps for Stronger Retail Relationships
Plan a useful iPOS customer mobile app around real customer journeys, clear records and consistent service, with owner and customer responsibilities kept…
Ecommerce Stores, iPOS Web POS and Infinity ERP
Plan an ecommerce store alongside iPOS Web POS and Infinity ERP, with clear ownership of products, stock, orders, fulfilment and customer-facing informati…