Supplier Shortages and Returns: Close the Receiving Exception
Supplier exceptions should connect the delivered goods, receiving record, outstanding commitment and agreed commercial resolution. iPOS requirements should show how staff identify and resolve those differences instead of treating every delivery as complete and correct.
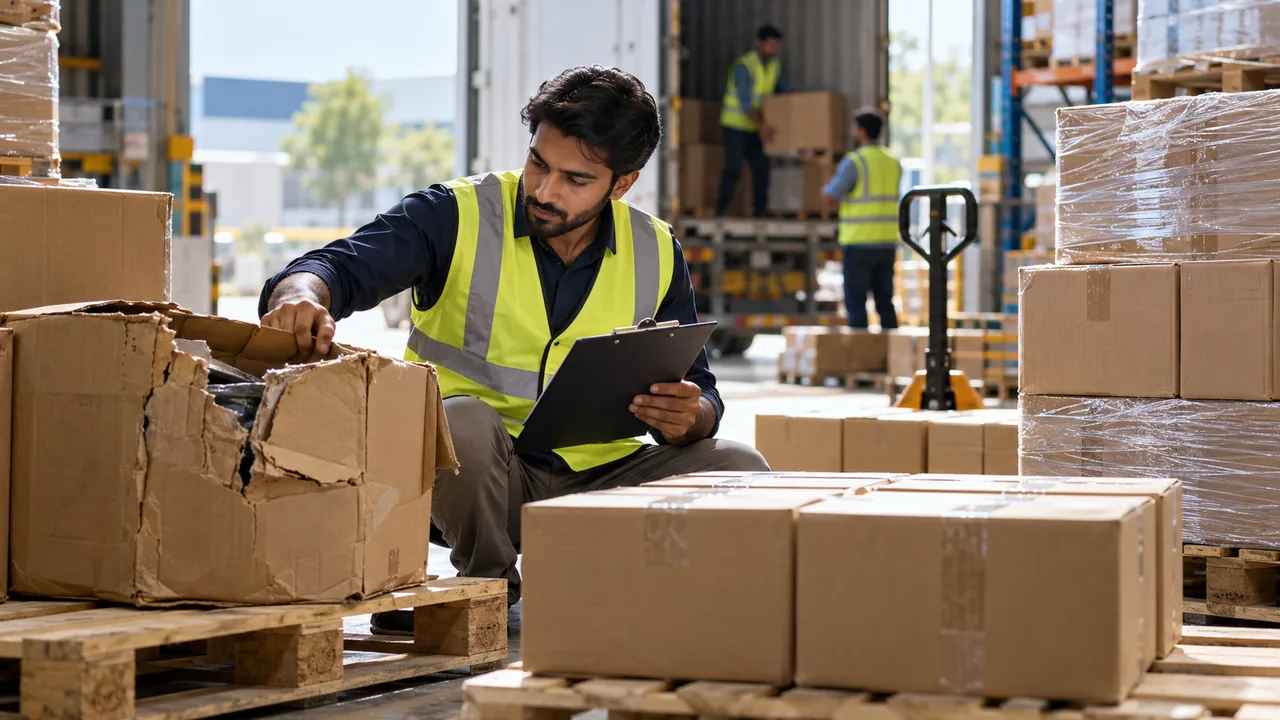
AI-generated editorial illustration.
Record what actually arrived
Compare the delivery with the intended order, units and relevant product detail. Separate accepted, damaged, unexpected and missing goods according to the business process. Identify the person authorized to decide the next action. An accurate receiving record is the starting point for a useful supplier conversation and for keeping ordinary stock availability understandable.
Keep the claim linked to its source
A shortage or return may affect a replacement delivery, credit, payment or remaining order quantity. Define the intended references and the staff responsible for communicating with the supplier. Demonstrate a partial resolution rather than assuming the matter ends as soon as a note is entered. The scope should identify the supported operational and financial records and any additional workflow required.
Review unresolved work and recurring causes
Assign an owner and a review rhythm for open exceptions. Distinguish awaiting information from an approved resolution that has not yet been recorded. Review patterns in unit mistakes, damage or incomplete supply before changing purchasing decisions. The objective is a maintainable process that closes real differences, not a growing list of complaints detached from stock and finance.
A practical scenario
A supplier delivers fewer units than ordered and accepts a return of damaged goods. The demonstration follows the accepted stock, outstanding quantity and intended commercial adjustment separately. Purchasing and finance can then identify what remains unresolved without recreating the original delivery.
Demonstration and acceptance checklist
| Action to demonstrate | Evidence to inspect |
|---|---|
| Check the delivered quantities | Accepted and exceptional goods are distinguished |
| Create the required reference | The claim remains linked to its source |
| Record a partial resolution | Outstanding responsibility remains visible |
| Review the financial treatment | The approved commercial outcome is traceable |
Questions buyers ask
Does a supplier return always have the same financial effect?
No. The agreed replacement, credit or other resolution determines the required treatment.
Who should own an unresolved claim?
Assign a responsible role and an escalation route rather than leaving the matter between departments.
Relevant iPOS options
Related guides
- Seasonal Stock Transfers: Move the Right Goods Before Demand Changes
- Online Stock Exceptions: Resolve Overselling, Cancellations and Delays
- Chain-Store Stock Optimization: Balance Availability Across Branches
Compare the iPOS product range or contact iPOS about your requirements.
More from Insights
Promotion Bundles: Price, Stock and Return Controls
A promotion bundle should have a clear commercial rule and an understandable effect on stock, payment and returns. Ask iPOS to demonstrate the required pr…
Quantity Discounts: Test the Threshold, Unit and Margin
Quantity discounts should identify the eligible unit, threshold and price rule. A useful iPOS demonstration tests the values immediately below, at and abo…
Customer-Specific Pricing Without Uncontrolled Overrides
Customer-specific pricing should apply an agreed commercial arrangement to an identifiable customer without giving every operator unrestricted price contr…