Returns and Exchanges: A Policy the POS and Staff Can Follow
A workable returns policy defines eligibility, references, approvals and the treatment of stock and payment. iPOS configuration should be demonstrated against that policy, including ordinary and exceptional cases rather than only a simple full refund.
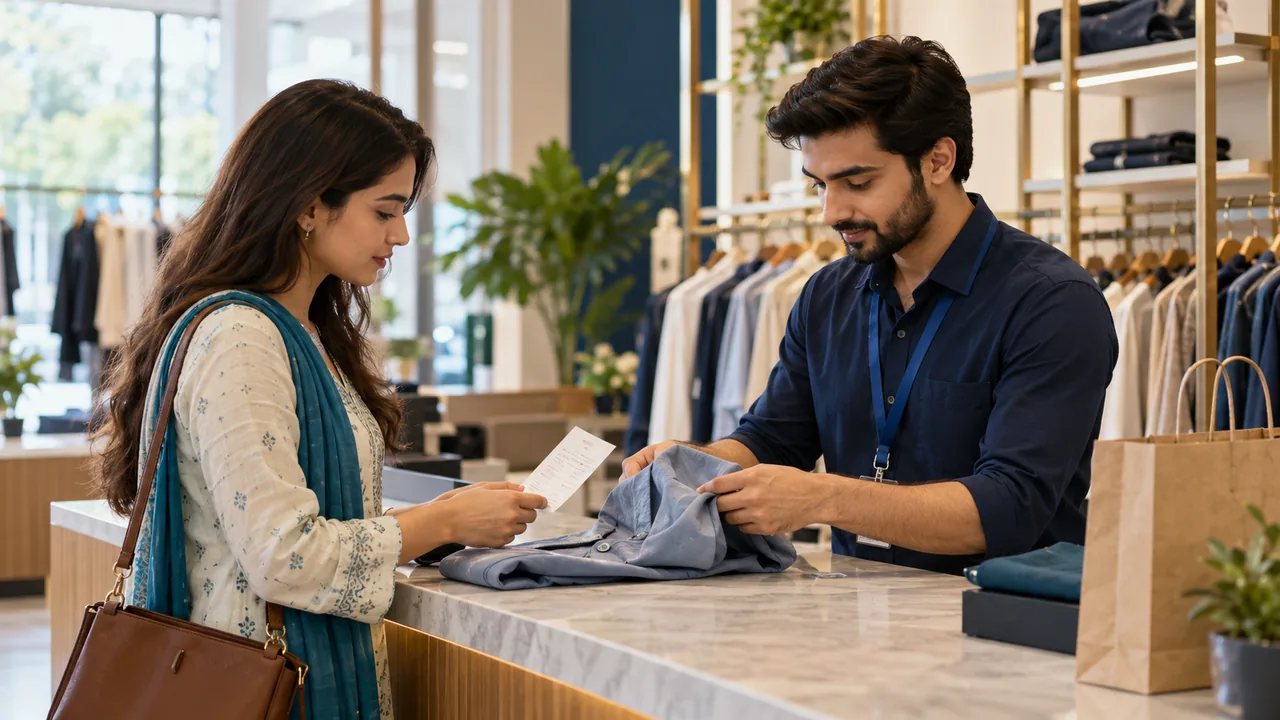
AI-generated editorial illustration.
Make the policy operationally specific
Identify the information staff need to decide what action is permitted. Include the original sale reference, condition of the goods, relevant period and the difference between exchange and refund. Policies may vary by product or transaction type. Staff should not have to invent a rule at the counter because the written policy describes a principle but not the next responsible action.
Follow both goods and money
An exchange can involve another variant or a price difference. A returned product may be saleable, damaged or subject to another agreed treatment. Demonstrate the resulting stock and financial records for each required case. The visual simplicity of a return screen does not prove that the business can explain where the item and payment ended up.
Use approvals and review constructively
Define the situations requiring a supervisor and the information retained for later review. Avoid controls so broad that normal staff cannot complete ordinary work, but do not grant unrestricted authority solely to shorten a process. Review recurring issues to identify product, training or policy problems. The software should support the agreed responsibility rather than substitute for a policy nobody has approved.
A practical scenario
A customer exchanges an apparel item for another size at a different price. The demonstration follows the original reference, approval, returning variant, outgoing variant and settlement difference. Staff then explain the result using the same policy that management expects them to apply during trading.
Demonstration and acceptance checklist
| Action to demonstrate | Evidence to inspect |
|---|---|
| Find the original sale | The correct reference supports the decision |
| Exchange a variant | Both stock movements are understood |
| Handle non-saleable goods | Availability follows the approved treatment |
| Review an exception | Authorization and commercial effect are traceable |
Questions buyers ask
Should a return always restore ordinary sellable stock?
Not necessarily. Follow the item's condition and the business's approved workflow.
Can one return demonstration prove every policy case?
No. Include the exceptions and product types that matter to the particular business.
Related guides
- Price Changes: Approval, Effective Dates and a Clear Audit Trail
- Cycle Counts: Check Inventory Without Closing the Whole Store
- Chain-Store Stock Optimization: Balance Availability Across Branches
Compare the iPOS product range or contact iPOS about your requirements.
More from Insights
Promotion Bundles: Price, Stock and Return Controls
A promotion bundle should have a clear commercial rule and an understandable effect on stock, payment and returns. Ask iPOS to demonstrate the required pr…
Quantity Discounts: Test the Threshold, Unit and Margin
Quantity discounts should identify the eligible unit, threshold and price rule. A useful iPOS demonstration tests the values immediately below, at and abo…
Customer-Specific Pricing Without Uncontrolled Overrides
Customer-specific pricing should apply an agreed commercial arrangement to an identifiable customer without giving every operator unrestricted price contr…