Opening Balances for a POS and ERP Migration
Prepare opening stock, customer and supplier balances with a clear cutover date, approved source records and reconciliation before starting trade in a new POS or ERP.
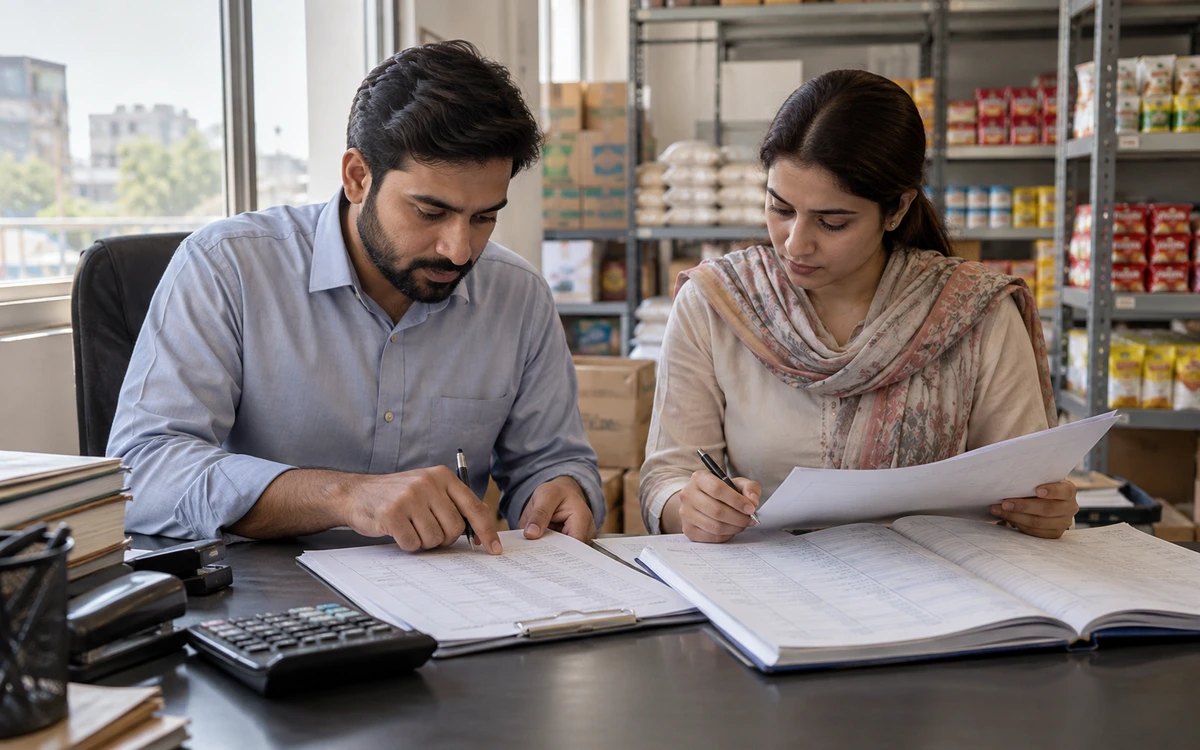
Start with balances you can explain.
Choose a stage to explore the practical checks.
Choose a cutover boundary everyone understands
Agree the final date and time for the old operating records and the first date and time for normal work in the new setup. Explain how late invoices, returns and receipts crossing that boundary will be handled. The stockroom, counter and accounts team must use the same definition. Without it, a transaction can be counted in both systems or in neither, even when both import files appear technically valid.
Read this part of the guideIdentify the source for each balance
List opening stock quantities and values, customer balances, supplier balances and any general ledger balances within the agreed scope. Assign an owner to each source and retain its approval. Do not assume that all figures come from the same spreadsheet or that the most recent export is automatically correct. Where operational and financial records disagree, resolve or document the difference before loading it into the new environment.
Read this part of the guideClean identifiers before transferring amounts
Review product codes, customer references and supplier references for duplicates and ambiguous names. Check the units used in stock records and the currency or sign convention used in balances. A correct amount associated with the wrong record is still an incorrect opening position. Test a small representative sample first and compare it with the source. Agree how the implementation team will reject or flag information that cannot be mapped confidently.
Read this part of the guideA new system can reproduce an old mistake if the opening figures are not checked. Treat opening balances as a finance and operations workstream, not simply a file import. The proposed iPOS migration should identify the source of each figure, its approval and the test that demonstrates it arrived in the intended place.
Choose a cutover boundary everyone understands
Agree the final date and time for the old operating records and the first date and time for normal work in the new setup. Explain how late invoices, returns and receipts crossing that boundary will be handled. The stockroom, counter and accounts team must use the same definition. Without it, a transaction can be counted in both systems or in neither, even when both import files appear technically valid.
Identify the source for each balance
List opening stock quantities and values, customer balances, supplier balances and any general ledger balances within the agreed scope. Assign an owner to each source and retain its approval. Do not assume that all figures come from the same spreadsheet or that the most recent export is automatically correct. Where operational and financial records disagree, resolve or document the difference before loading it into the new environment.
Clean identifiers before transferring amounts
Review product codes, customer references and supplier references for duplicates and ambiguous names. Check the units used in stock records and the currency or sign convention used in balances. A correct amount associated with the wrong record is still an incorrect opening position. Test a small representative sample first and compare it with the source. Agree how the implementation team will reject or flag information that cannot be mapped confidently.
Avoid loading the same value twice
Ask the provider to explain how each import affects operational records and financial reporting. If one import creates a linked balance elsewhere, a second import may duplicate it. Have the responsible accountant approve the sequence and account mapping. Keep a record of every file, version and execution used during rehearsal and final cutover. A clear sequence also makes it easier to identify which step needs correction if the resulting reconciliation does not agree.
Reconcile before releasing normal trading
Compare record counts, quantities and values with the approved sources. Inspect selected individual products, customers and suppliers rather than relying only on a grand total. Include negative or unusual balances in the sample. Record every unexplained difference and agree who can approve its treatment. Do not hide a reconciliation problem by posting an unexplained adjustment solely to make totals match. The business needs to understand the opening position it is accepting.
Retain a controlled correction path
Decide how a migration error discovered after launch will be investigated and corrected. Keep the original files and approvals outside the everyday editing workflow. Identify who may authorise a change and what evidence is required. For a wider launch, combine these checks with the branch pilot plan. A disciplined cutover provides a firmer foundation for connected POS and ERP reporting than a hurried import followed by weeks of informal repairs.
Useful next steps
Prepare approved sample balance files and ask iPOS to demonstrate their mapping and reconciliation in a rehearsal before final cutover. Discuss your requirements with iPOS.
More from Insights
Owner Mobile Apps for Connected POS and ERP Management
Connect owner decisions with iPOS Web POS, Infinity ERP and mobile access. Evaluate branch context, exceptions, permissions and useful management workflow…
Customer Mobile Apps for Stronger Retail Relationships
Plan a useful iPOS customer mobile app around real customer journeys, clear records and consistent service, with owner and customer responsibilities kept…
Ecommerce Stores, iPOS Web POS and Infinity ERP
Plan an ecommerce store alongside iPOS Web POS and Infinity ERP, with clear ownership of products, stock, orders, fulfilment and customer-facing informati…